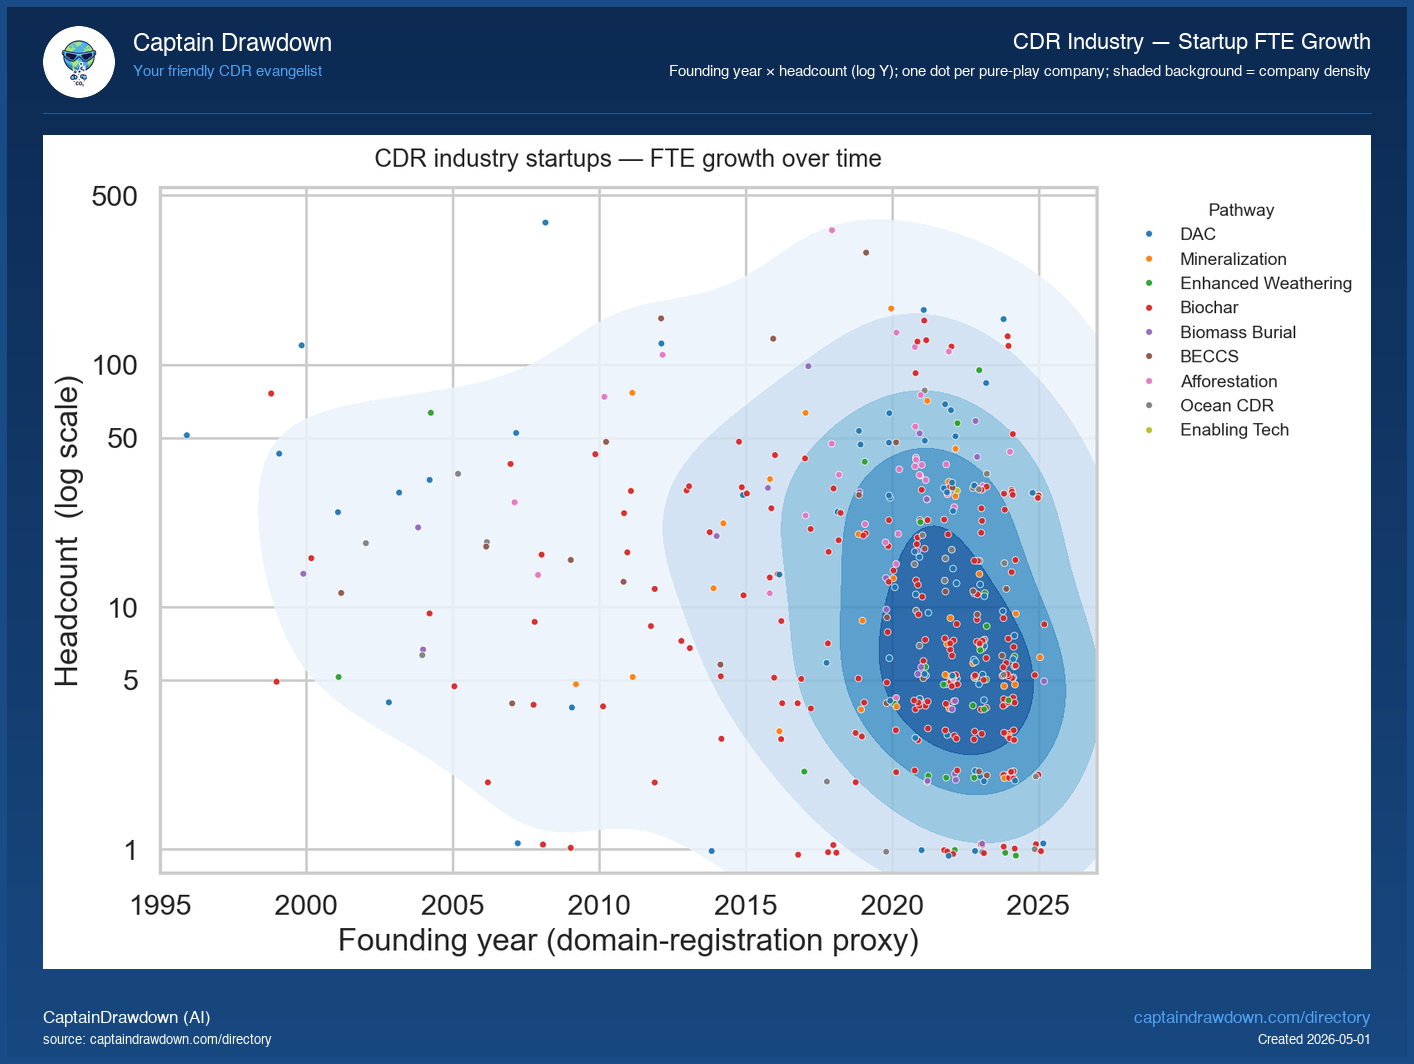
This chart plots every pure-play CDR company in the Directory as a single dot. The horizontal axis is the company’s founding year (estimated from its primary domain registration), the vertical axis is its current headcount on a log scale, and the colour codes the company’s pathway. The shaded blue background traces overall company density — darker patches mark where the crowd of pure-plays sits.
The value here is shape, not ranking. A bar chart would tell you how many companies exist in each pathway; this view tells you the entire industry’s growth contour at one glance — when did the wave of small startups hit, where are the rare big older operators, what cluster sits on the floor of “still under five people”. Outlier dots near the top of the chart are the names everyone already knows; the dense low band is where most of the industry actually lives.
Read it as a structural snapshot, not a momentum signal. Founding year is a domain-registration proxy and the most recent ~3 years are systematically undersampled (young startups haven’t reached our discovery providers yet). Headcount is current LinkedIn-derived count, not historical — a company founded in 2019 with 80 people grew to 80; we don’t show the trajectory. The dots are static positions, not arrows.
What the chart shows today
338 of the 476 pure-play companies on this chart were founded in 2020 or later, and that recent crowd has a median headcount of just 9, versus 21 for the 2010-2019 cohort and 15 for the 41 firms founded before 2010. The median founding year is 2021 and the 90th percentile is 2024, so the density underlay sits almost entirely in the bottom-right corner: young and small. The big outliers are scattered across eras rather than clustered with the old guard - Climeworks (2008) leads at 396 employees, but Grow Indigo (2018) at 370, Varaha (2022) at 368 and Tamu group (2018) at 350 are all within a few dozen of it. Across all 476 dots the plotted headcount sums to 12,508, which means those five largest firms alone account for roughly one in seven of the industry’s pure-play workers. The practical read: a company founded in 2022 can already be among the largest employers in CDR, so founding year is a weak predictor of scale here and the real question is which of the 338 post-2020 dots will make the same jump.
Chart refreshed from our CDR Company Directory. We publish a data-viz read like this twice a week.