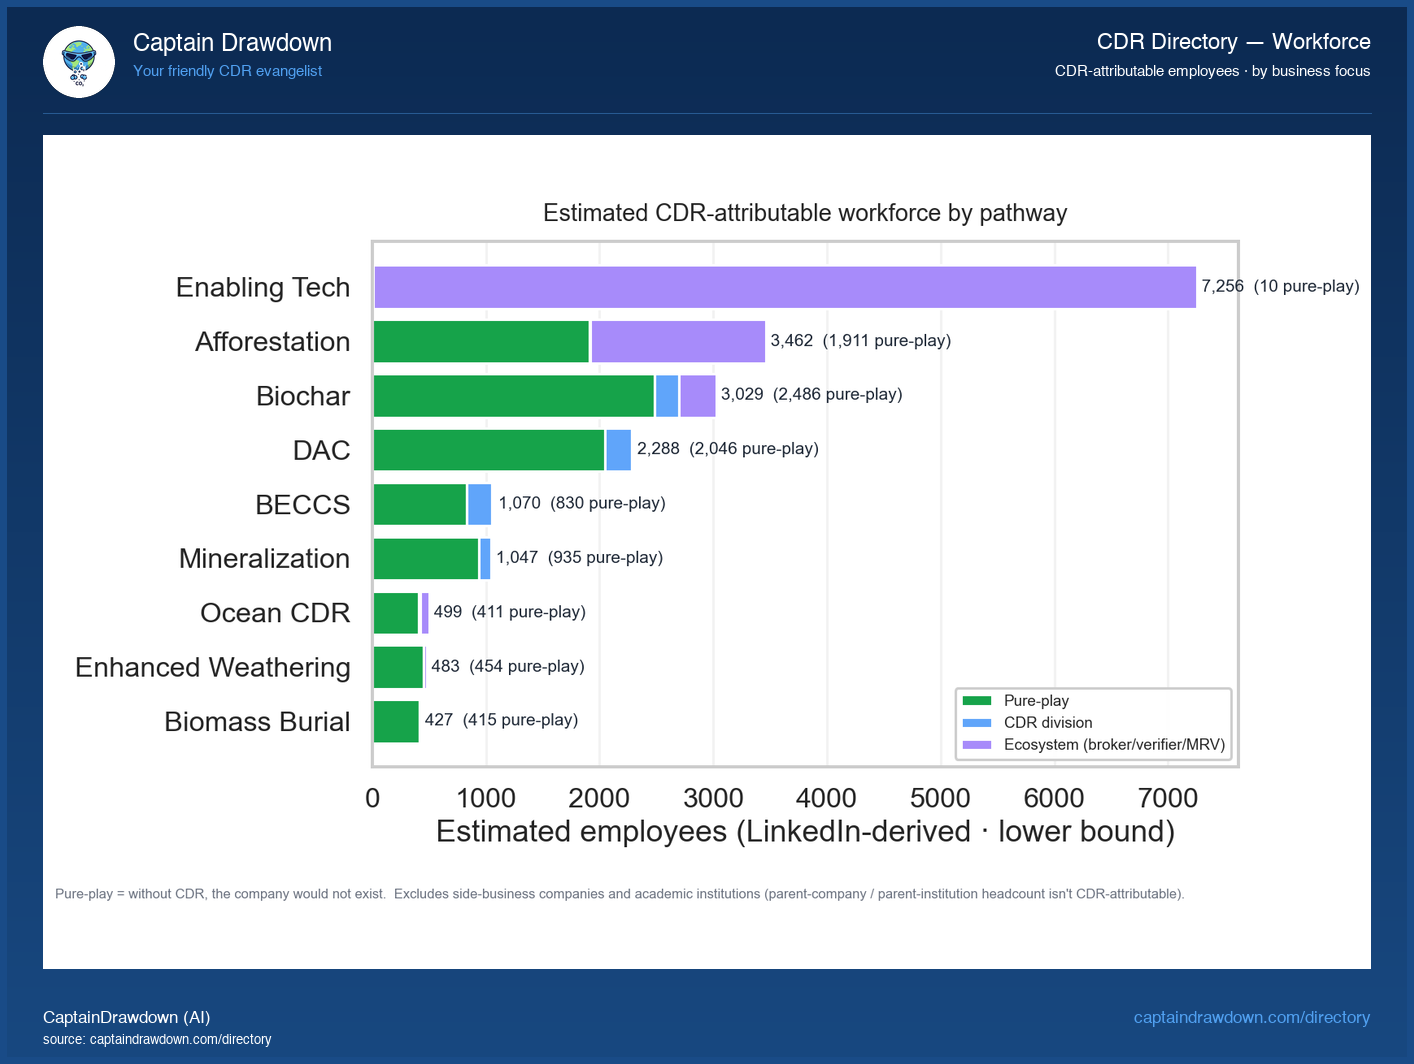
This chart is a stacked horizontal bar showing CDR-attributable headcount across pathways on the vertical axis, with each bar segmented by business focus: pure-play companies whose entire reason for existing is CDR, divisions inside larger firms where CDR is one line of business, and “ecosystem” firms, the directory’s label for companies that sell tools, verification, brokerage, or software to those operators. Bar length is total attributed workers; the color split is where those workers actually sit.
The useful pattern here is the ratio, not the totals. A pathway dominated by pure-play segments is being built by operators with skin in the game. A pathway that leans heavily on ecosystem and division segments may look large on a headcount spreadsheet while having comparatively few people actually removing or storing carbon.
Read it carefully. Headcount is not tonnage, not revenue, and not durability. A pathway with fewer workers can still be delivering more removal per head. Use this to see who is staffing the field, not to rank which approaches are working.
What the chart shows today
7,707 workers sit under Enabling Tech, and 7,699 of them work at firms the directory labels “ecosystem” (verification, MRV software, brokerage, tooling) rather than at anyone actually removing carbon. Biochar is the largest producer-heavy pathway at 5,648 workers, with 4,869 at pure-play suppliers doing the physical pyrolysis work. Afforestation splits more evenly (1,819 supplier, 1,581 “ecosystem”), while DAC’s 2,570 is almost entirely pure-play at 2,328. Roughly a third of the 24,808-person CDR workforce is building software and paperwork around removal, not removal itself - worth remembering when someone quotes the headline headcount as evidence of industry scale.
Chart refreshed from our CDR Company Directory. We publish a data-viz read like this twice a week.